UK Non-Dom Rules Have Changed: The New FIG Regime and Inheritance Tax Explained
Subscribe to our newsletter for the latest expatriate news, views & analysis.
The UK’s tax rules for non-domiciled individuals have undergone one of their biggest changes in decades.
From 6 April 2025, the traditional non-dom regime and remittance basis were replaced by a new system focused much more heavily on UK tax residence.
For British expats considering returning to the UK, foreign nationals moving to Britain, and internationally mobile individuals with overseas investments and assets, the changes create both opportunities and potential tax traps.
One of the most significant opportunities is the new four-year Foreign Income and Gains (FIG) regime.
At the same time, the UK has fundamentally changed how Inheritance Tax (IHT) applies to overseas assets.
The result is a system where understanding not only where you live today, but where you have been tax resident over the previous 10 or 20 years, can be crucial.
What Happened to the UK Non-Dom Regime?
Historically, an individual's domicile could have a major influence on how the UK taxed their foreign income, gains and estate.
A UK resident who was considered non-UK domiciled could, subject to the relevant rules, use the remittance basis and potentially avoid UK tax on certain foreign income and gains provided they were kept outside the UK.
That system ended on 6 April 2025.
UK residents are now generally taxed on the arising basis on their worldwide income and gains, regardless of their domicile. In place of the old remittance basis, the government introduced a new residence-based regime for qualifying new UK residents.
For people moving to the UK after a substantial period overseas, that new regime can be extremely important.
The New 4-Year Foreign Income and Gains (FIG) Regime
An individual who becomes UK tax resident following at least 10 consecutive tax years of non-UK residence may qualify for the new FIG regime.
Qualifying individuals can claim relief from UK tax on eligible foreign income and foreign gains arising during their first four tax years of UK residence.
This could potentially include qualifying:
Foreign investment income
Overseas dividends
Foreign interest
Rental income from overseas property
Gains arising from certain overseas investments and assets
This represents a major change from the old non-dom system.
Rather than asking where somebody is domiciled, eligibility for the FIG regime is principally determined by their recent tax residence history.
Returning British Expats Can Qualify Too
One particularly important aspect of the new rules is that the FIG regime is not restricted to foreign nationals.
A British citizen returning to the UK may also qualify.
For example, consider someone who left the UK and spent more than 10 consecutive tax years living and working overseas.
If they subsequently return and become UK tax resident again, they may potentially qualify for FIG relief during their first four years back in the UK, assuming the relevant conditions are satisfied.
For long-term British expats considering a return home, this makes the timing of the move potentially very important.
Returning shortly before completing the required period of non-residence could produce a very different tax position from returning after the qualifying period has been achieved.
The Four Years Start When UK Residence Starts
There is another important point to understand: the four-year period is not a bank of four years that can simply be used whenever convenient.
It is linked to the individual's first four tax years of UK residence following the qualifying period of non-residence.
If someone temporarily becomes non-UK resident during that four-year period, they cannot simply save the unused FIG year and add it to the end.
Careful residence planning can therefore be important before a move takes place.
FIG Relief Has to Be Claimed
The FIG regime is not simply an automatic four-year exemption from all UK taxation.
Relief must be claimed for the relevant foreign income and gains.
There are also consequences to making a claim. In particular, an individual claiming FIG relief can lose their entitlement to certain UK tax allowances for that tax year, including the Income Tax personal allowance and Capital Gains Tax annual exempt amount.
Whether a FIG claim is advantageous therefore depends on the individual's circumstances, income and assets.
It should not automatically be assumed that making the claim produces the best result in every case.
What About Money Brought Into the UK?
One major difference between the new FIG regime and the old remittance basis concerns bringing overseas money into Britain.
Under the former remittance basis, bringing certain foreign income and gains into the UK could itself trigger UK taxation.
Under the FIG regime, eligible foreign income and gains for which FIG relief has been claimed can generally be brought to the UK without an additional UK tax charge simply because they have been remitted.
For qualifying internationally mobile individuals, that can make the new regime considerably easier to navigate than the old remittance-basis system.
Inheritance Tax Has Changed Too
The reforms go considerably further than income and Capital Gains Tax.
From 6 April 2025, the UK also moved away from domicile as the central test for determining whether an individual's overseas assets fall within the scope of UK Inheritance Tax.
The new system introduces the concept of a long-term UK resident.
Broadly, an individual can become a long-term UK resident where they have been UK tax resident for at least 10 of the previous 20 tax years.
Once an individual falls within the long-term residence rules, their non-UK assets may also become subject to UK Inheritance Tax.
That makes historical residence increasingly important for estate planning.
The 10-Out-of-20-Year IHT Test
Consider an internationally mobile individual who owns assets in several countries.
If they have spent only a relatively short period in the UK, their overseas assets may remain outside the scope of UK IHT, subject to the detailed rules.
However, once their UK residence history reaches the long-term residence threshold, the position can change substantially.
An individual who has been UK resident for at least 10 out of the preceding 20 tax years can potentially find their worldwide estate within the UK IHT regime.
This can affect assets such as overseas property, investment portfolios and other foreign assets.
UK assets can, of course, remain subject to UK IHT regardless of whether an individual is a long-term UK resident.
Leaving the UK Does Not Necessarily End IHT Exposure
This is perhaps one of the most important elements of the new rules for British expats and people planning to leave the UK.
Becoming non-UK resident does not necessarily mean that overseas assets immediately fall outside UK Inheritance Tax.
A former long-term UK resident can remain within the regime for a period after departure.
The length of this "tail" depends on how many years the individual had previously been UK resident.
Broadly:
UK residence before leavingPotential period remaining within long-term residence rules10–13 years3 tax years14 years4 tax years15 years5 tax years16 years6 tax years17 years7 tax years18 years8 tax years19 years9 tax years20 years10 tax years
This means someone with a long history of UK residence could potentially remain within the long-term residence rules for up to 10 tax years after leaving the UK.
Simply moving overseas is therefore not necessarily enough to immediately remove foreign assets from UK IHT exposure.
Ten Years Overseas Can Reset the Position
There is an important interaction between the FIG and IHT regimes.
After 10 consecutive tax years of non-UK residence, the long-term residence test can effectively reset.
If the individual then returns to the UK, their earlier residence history will not immediately make them a long-term resident again for IHT purposes.
At the same time, completing 10 consecutive years of non-UK residence can allow the individual to meet the residence-history requirement for the four-year FIG regime when returning to Britain.
For long-term expats contemplating a future return to the UK, the 10-year point can therefore be particularly significant.
Example: A British Expat Returning to the UK
Consider a British citizen who has lived in Cyprus for the last 12 tax years and has remained non-UK resident throughout that period.
They have built up an overseas investment portfolio and receive foreign investment income.
If they return to Britain and become UK tax resident, they may potentially qualify for the four-year FIG regime because they have completed at least 10 consecutive tax years of non-UK residence.
Subject to the detailed conditions and making the appropriate claims, eligible foreign income and gains could receive FIG relief during their qualifying four-year period.
Their British citizenship itself does not prevent them from accessing the regime.
This is why returning expats should ideally examine their tax position before establishing UK residence, rather than after the move has already taken place.
Example: Leaving the UK After 15 Years
Now consider someone who has been UK tax resident for 15 of the previous 20 tax years before relocating overseas.
They may cease to be UK resident for Income Tax and Capital Gains Tax purposes, but their overseas assets do not necessarily immediately escape the UK IHT regime.
Under the long-term residence rules, someone with 15 years of relevant UK residence can remain within the long-term UK residence regime for five tax years after leaving.
Their residence status for annual taxation and their exposure to IHT on worldwide assets therefore need to be considered separately.
Why This Matters for International Relocation Planning
The UK's new system makes the timing of international moves increasingly important.
For someone considering moving to the UK, questions may include:
How many complete tax years have I been non-UK resident?
Would waiting until I have completed 10 consecutive tax years overseas allow me to qualify for FIG relief?
When will my four-year FIG period begin?
For somebody considering leaving the UK, the questions are different:
How many of the previous 20 tax years have I been UK resident?
Am I already a long-term UK resident for IHT purposes?
How long could my worldwide assets remain exposed to UK IHT after departure?
These are no longer simply questions about domicile.
They are increasingly questions about residence history and timing.
Don't Forget the Statutory Residence Test
Determining whether someone is UK resident is itself not always straightforward.
UK residence is generally established using the Statutory Residence Test (SRT), which considers factors including days spent in the UK and, depending on the circumstances, connections with the UK.
Someone planning their affairs around the FIG or long-term residence rules should therefore avoid assuming that simply "living abroad" automatically means they have been non-UK resident for the required number of tax years.
Their actual tax residence position should be established for each relevant year.
Existing Trusts and Offshore Structures Need Particular Care
Individuals with offshore trusts or more complicated international structures should obtain specific advice.
The new residence-based IHT rules also affect the treatment of foreign assets held within settlements, and the treatment can depend on factors including the settlor's long-term residence status and transitional provisions.
Historic planning undertaken under the old domicile regime should therefore not automatically be assumed to produce the same result under the new system.
Planning Before You Move Is Increasingly Important
There is a broader lesson from the reforms.
International tax planning is often most effective before a change of residence takes place.
Once an individual has moved, become tax resident, sold an asset, received income or otherwise triggered a tax event, some planning opportunities may already have disappeared.
For British expats thinking about returning home, individuals considering moving to Britain and UK residents contemplating relocation overseas, it can therefore be worth reviewing:
Current and historic tax residence
The proposed date of relocation
Overseas income and investments
Unrealised capital gains
UK and overseas property
Existing trusts and structures
Wills and estate planning
Potential UK Inheritance Tax exposure
Tax obligations in the destination country
Any applicable double taxation agreements
The UK rules should also be considered alongside the tax regime of the other country involved. Leaving the UK tax system does not mean leaving taxation altogether, and different jurisdictions can define residence, income and estate taxation differently.
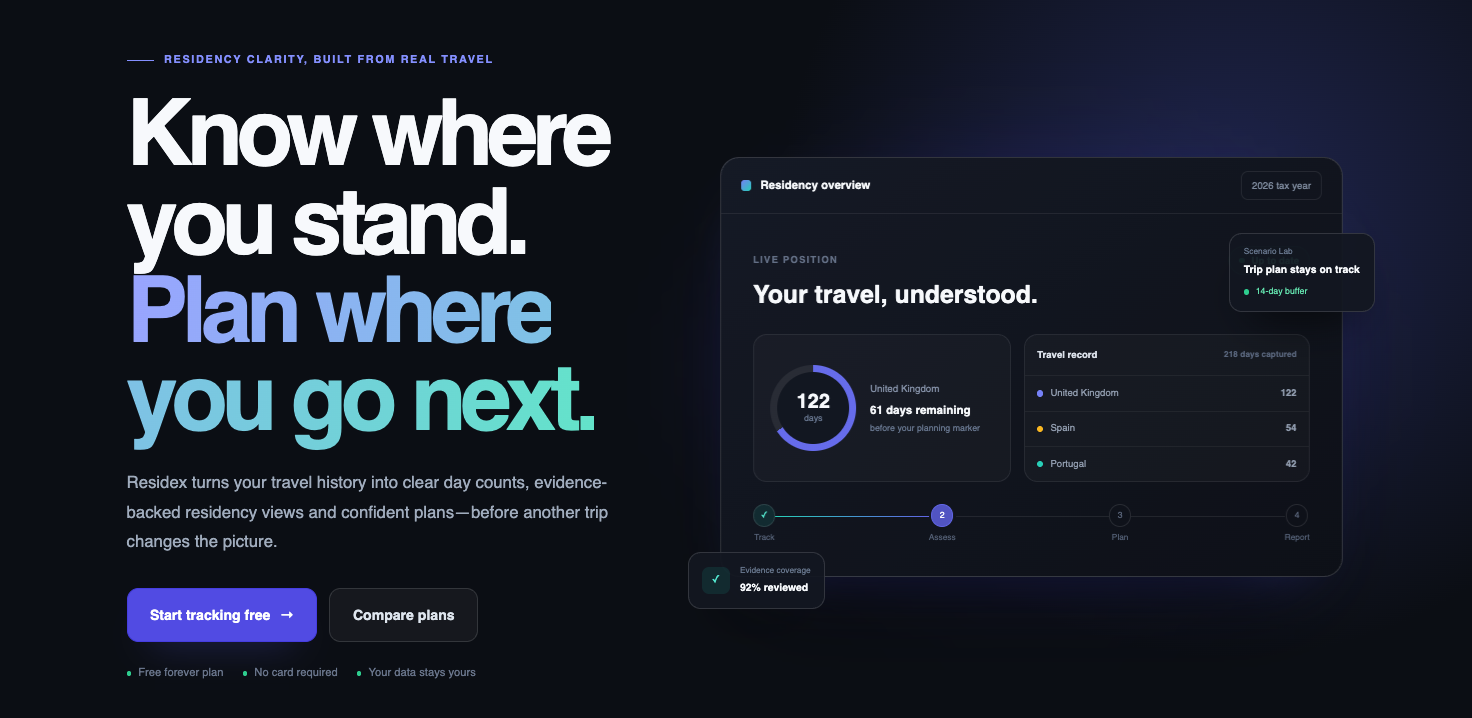
Use our tax residency tracker, Residex, for free to help track and plan your tax residency.
The New Reality for UK Expats
The abolition of the traditional non-dom regime does not mean that the UK has stopped offering tax advantages to internationally mobile individuals.
Instead, the focus has changed.
For new and returning residents, the four-year FIG regime can provide a potentially valuable period of relief from UK tax on qualifying foreign income and gains.
For longer-term residents, however, the new 10-out-of-20-year Inheritance Tax test means residence history can eventually bring worldwide assets within the UK IHT regime.
And for those leaving Britain, that exposure can potentially continue for between three and ten tax years, depending on their previous residence history.
The critical question is therefore no longer simply:
"Where am I domiciled?"
Increasingly, it is:
"Where have I been tax resident, for how long, and when should I move?"
For internationally mobile individuals, answering those questions before relocating can make a substantial difference.
International Tax and Residency Advice
We advises expats, returning UK nationals and internationally mobile individuals on UK tax residence, the FIG regime, Inheritance Tax and cross-border tax planning.
If you are considering moving to the UK, returning to Britain after living overseas, or leaving the UK, reviewing your position before the move can help identify both potential tax exposures and available planning opportunities.
Contact us

Need help & guidance?
Contact us or book a free review with one of our expat experts today.
Track your residency For Free
Residex helps you track, assess and plan your tax residency with clarity, evidence & confidence.